You're earning good money. But are you actually getting ahead?
You earn a good income. You've built up your super, invested in property and shares, and you're doing many of the things you're supposed to do financially.
From the outside, things look pretty good.
But here's a question worth asking: Are all those years of hard work actually bringing you closer to the life you want?
It's particularly relevant for successful professionals in their 40s and 50s. By this stage, many have accumulated considerable wealth, but also substantial financial commitments. They're earning more than ever, yet may still feel a long way from being able to slow down or retire.
Let's look at an example.
A successful couple with a question they can't answer
Consider a hypothetical couple, aged 48 and 46, with two school-aged children.
They earn a combined $350,000 a year and have spent two decades building their wealth.
But one partner is feeling increasingly burnt out and would love to stop full-time work at 55. The other is happy to continue working until 60.
They've started wondering whether this is financially possible.
Here's their financial position.
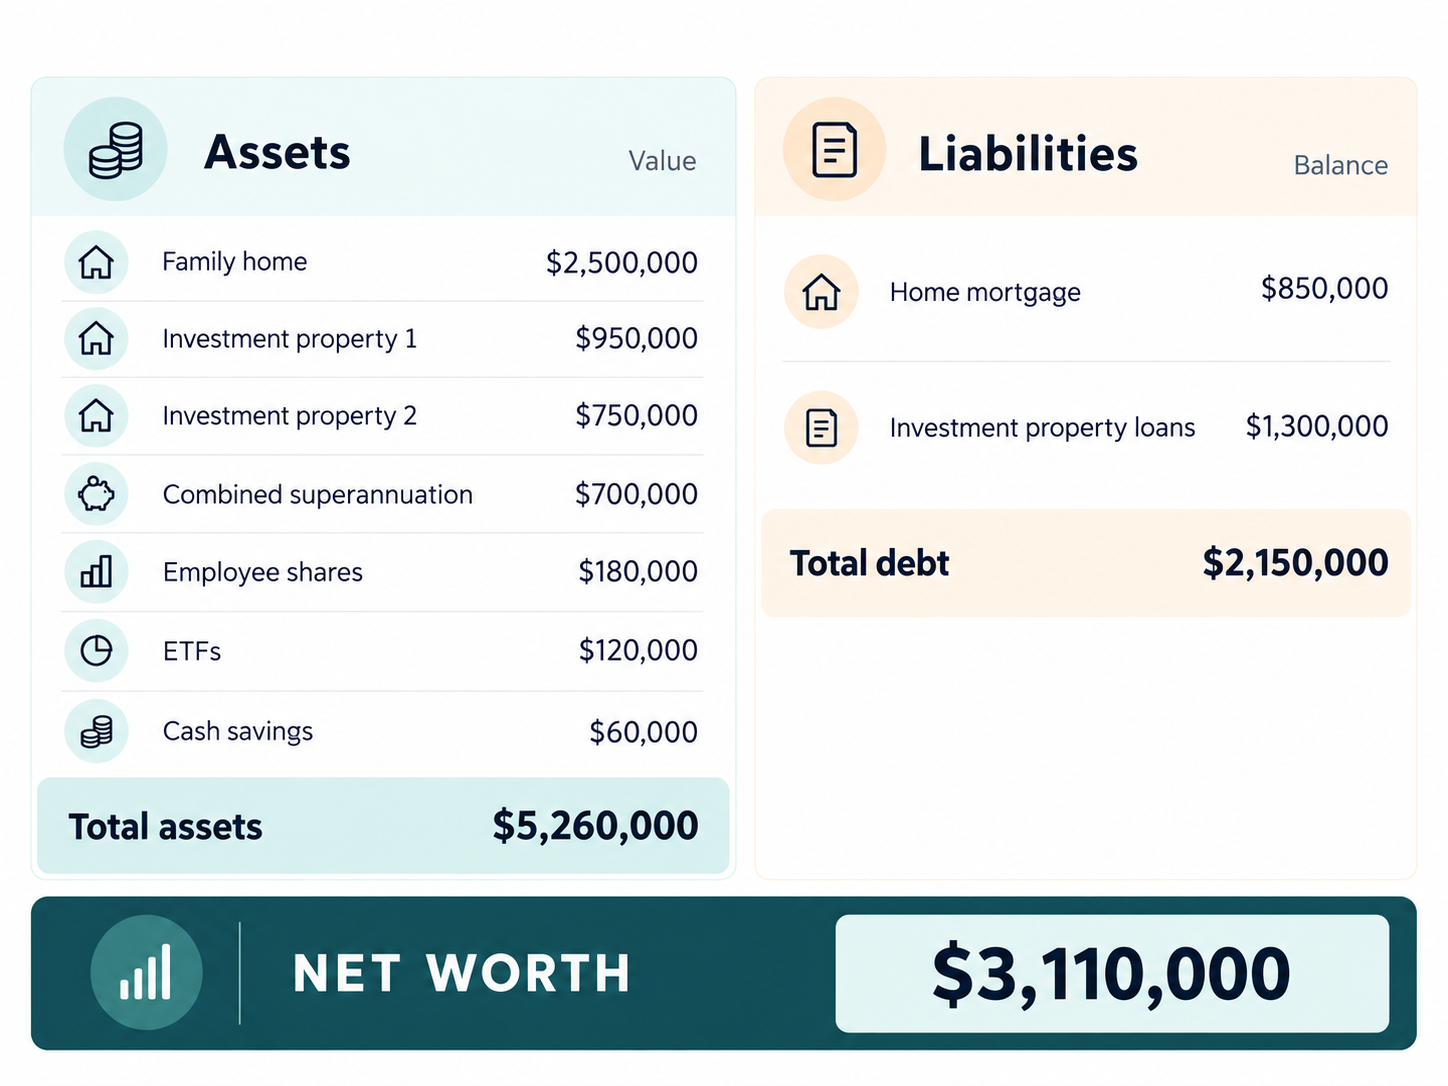
On paper, they've done very well. Three properties, substantial superannuation, investments outside super and a strong household income.
But their balance sheet doesn't answer their most important question.
Can one of them afford to stop working at 55 without compromising their financial future?
They have $2.15 million in debt, much of their wealth is tied up in property and super, and only $60,000 is held in cash.
None of this necessarily means they're financially stretched. But it does mean we need to look beyond their net worth to understand what choices they actually have.
Here's how I'd approach it.
1. When could work become optional?
The first step is understanding what retirement, or semi-retirement, would actually look like for them.
How much do they spend today? How might that change as their children become independent? What income would they need if one partner stopped working at 55?
Then we'd model different scenarios.
What if they both worked until 60? What if one stopped at 55? What if they gradually reduced their hours instead?
We'd also test whether those plans remain sustainable under less favourable investment returns and other reasonable assumptions.
This gives them something far more useful than a target net worth: an understanding of when they could afford to make work a choice rather than a necessity.
2. Is their wealth in the right places?
Our couple has $3.11 million in net wealth, but much of it is tied up in their home, investment properties and superannuation.
Their $700,000 in super generally won't be accessible until they meet a condition of release.
Outside property and super, they have $360,000 in employee shares, ETFs and cash.
If one partner stops working at 55, how would they fund the years before accessing super?
Could their investments and rental income support the transition? Would they need to draw down capital? Might selling an investment property be worth considering?
The question isn't simply whether they have enough wealth, but whether their assets are structured to provide money when they need it.
3. How much flexibility do their commitments leave them?
Our couple has $2.15 million in debt across their home and investment properties.
They may be managing the repayments comfortably on their current income. But what happens when one salary reduces or disappears?
Would the remaining income, rental income and investments be enough to cover their living expenses and loan commitments?
This doesn't mean taking on debt was a mistake. Borrowing may have helped them build substantial wealth.
But decisions that made sense during their accumulation years may need reconsidering as their priorities change.
The question is no longer just whether they can afford their lifestyle today, but whether it allows them to make the changes they want tomorrow.
4. Are their financial strategies working together?
Over the years, our couple has contributed to super, paid down mortgages, accumulated employee shares and invested in ETFs.
Each decision may have been sensible.
But now that early retirement is becoming a priority, do those strategies still work together?
For example, making additional super contributions could be tax-effective, but may not help fund the years before they can access super.
Keeping both investment properties might continue building wealth, but selling one could release capital and reduce debt, potentially making it easier to work less.
And their employee shares deserve attention too. Having both employment income and a substantial investment tied to the same company creates a concentration of risk worth examining.
None of these decisions has an obvious answer without understanding the full picture.
Good financial planning isn't about optimising every investment or financial decision separately. It's about making them work towards the same goals.
5. Could their plan withstand the unexpected?
Finally, we'd want to understand how resilient their position is.
What if one partner loses their job earlier than expected? What if interest rates rise or investment returns disappoint? What if the employer's share price falls just as their employment becomes uncertain?
With $2.15 million in debt and $60,000 in cash, these are important questions.
We'd examine their cashflow, offset accounts, insurance and other available resources before deciding whether changes are needed.
The goal isn't to eliminate every risk. That's neither possible nor desirable.
It's to make sure their financial future doesn't depend on everything going according to plan.
So, are they actually getting ahead?
Our hypothetical couple has accumulated more than $3 million in net wealth. That's a significant achievement.
But whether they're genuinely making financial progress depends on more than the size of their balance sheet.
I'd want to answer five questions:
Direction: When could work become optional?
Accessibility: Will their assets provide money when they need it?
Flexibility: Do their financial commitments support their future choices?
Coordination: Are their financial strategies working towards the same goals?
Resilience: Could their finances cope if circumstances change?
These questions give us a much better understanding of what their wealth can actually do for them.
Perhaps they'll discover that retiring at 55 is already achievable. Perhaps they'll need to restructure some investments, reduce debt or work a little longer.
We can't know without doing the analysis.
But at least they'll understand their options and what it would take to achieve them.
And that's the distinction I think matters.
Financial progress isn't just about having more money. It's about having more choices in how you live your life.
If you're earning good money but aren't sure whether your financial decisions are bringing you closer to the life you want, that's a conversation worth having.
The Bigger Financial Picture explores the decisions, trade-offs and strategies that shape our financial lives. At Maslow Wealth, we help people bring those pieces together so they can make better decisions with greater confidence.
